From Seasonal Incomes to Secure Retirements: Solving the Social Security Challenge for Farmers
Friday, October 23 2026 8:20 am
By Paul Busharizi, Financial Journalist
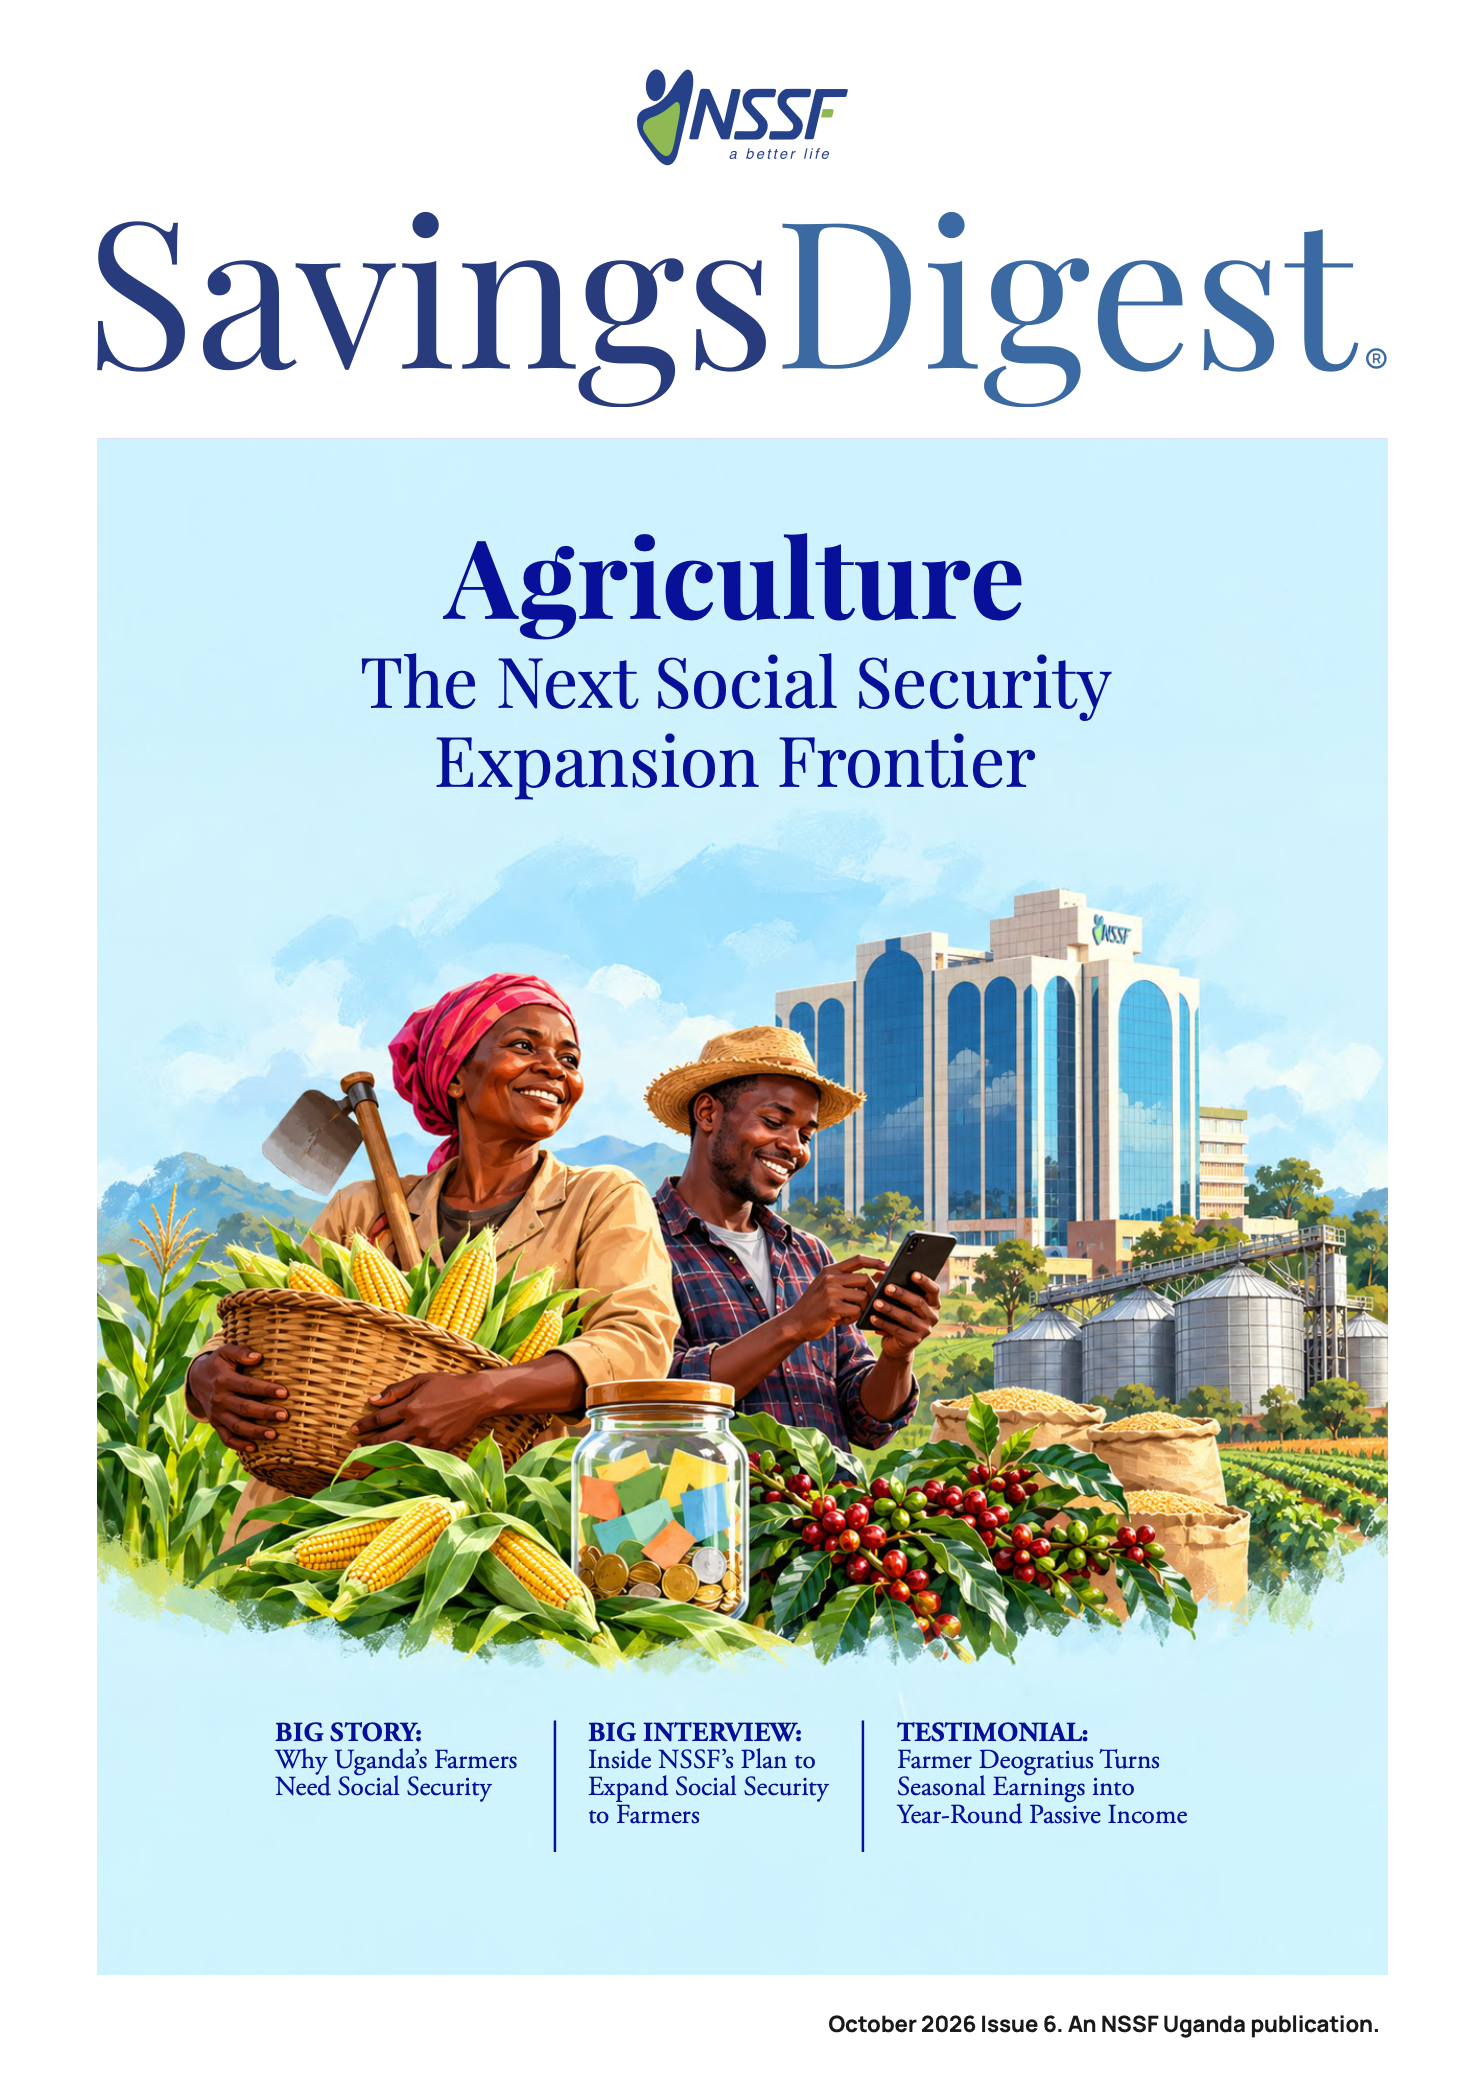
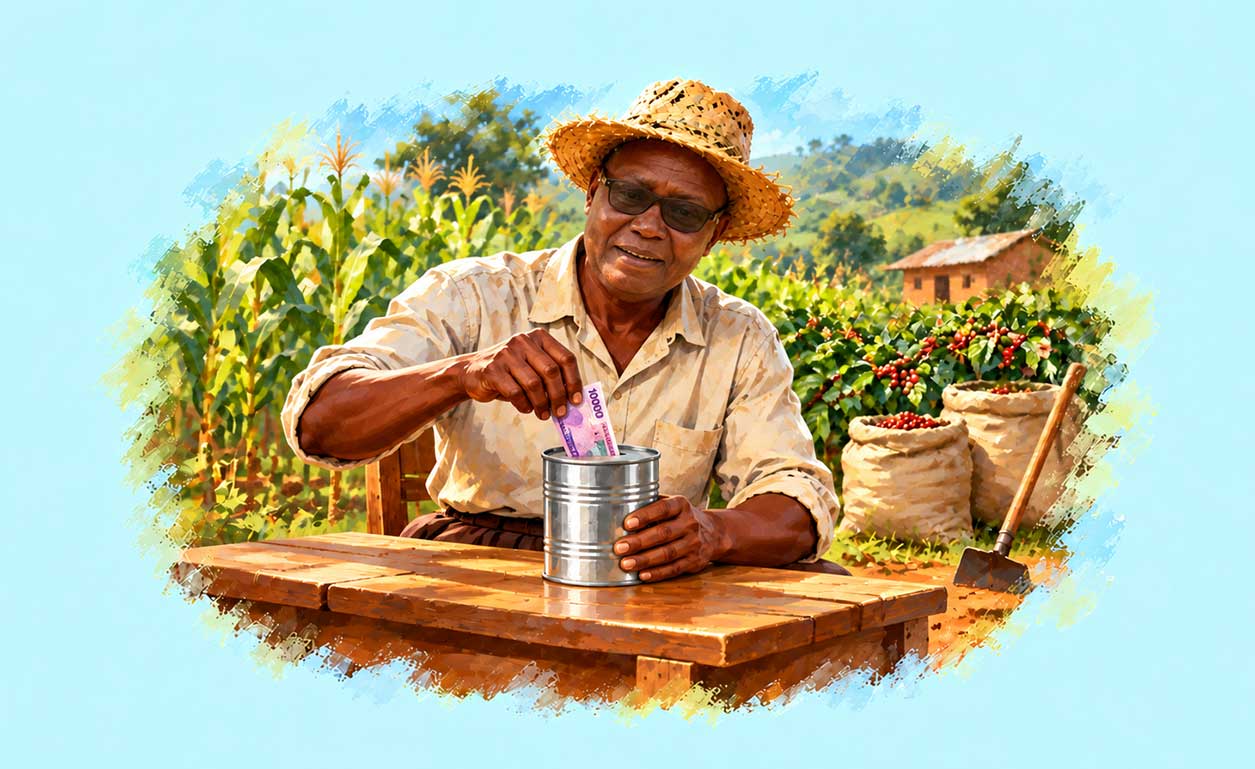
One Saturday morning in 2024, in Kyeizooba Subcounty, Bushenyi District, a coffee farmer in his late 50s sat under a mango tree counting the proceeds from his harvest. It had been a good season; his cooperative paid him nearly UGX 12 million, the largest lump sum of money he had ever received. His wife suggested putting some aside for old age. His friends advised him to buy another motorcycle. A local trader encouraged him to expand his coffee acreage.
A few months later, the money was all used up.
Part of it had paid school fees. He and his wife had raised six children through coffee farming. Some had gone into extending the family home. Much had simply been consumed by the relentless demands of daily life.
Today, he still works his coffee garden from dawn to dusk because he has no pension, no retirement savings and no safety net beyond the hope that his children will support him when he is too old to do much for himself.
His story is not unique. It is the story of millions of Ugandan farmers.
It illustrates one of the greatest policy challenges and opportunities Uganda faces today: how to extend social security services to agricultural workers, especially those operating in the informal economy.
The missing piece in Uganda’s social security system
Uganda’s formal social security framework has achieved remarkable success where it has been applied.
The Fund has grown into one of East Africa’s largest institutional investors. It manages trillions of shillings in assets, finances major infrastructure projects, supports capital markets and provides retirement savings for millions of workers.
Yet there is a paradox: the majority of Ugandans remain excluded from this success story.
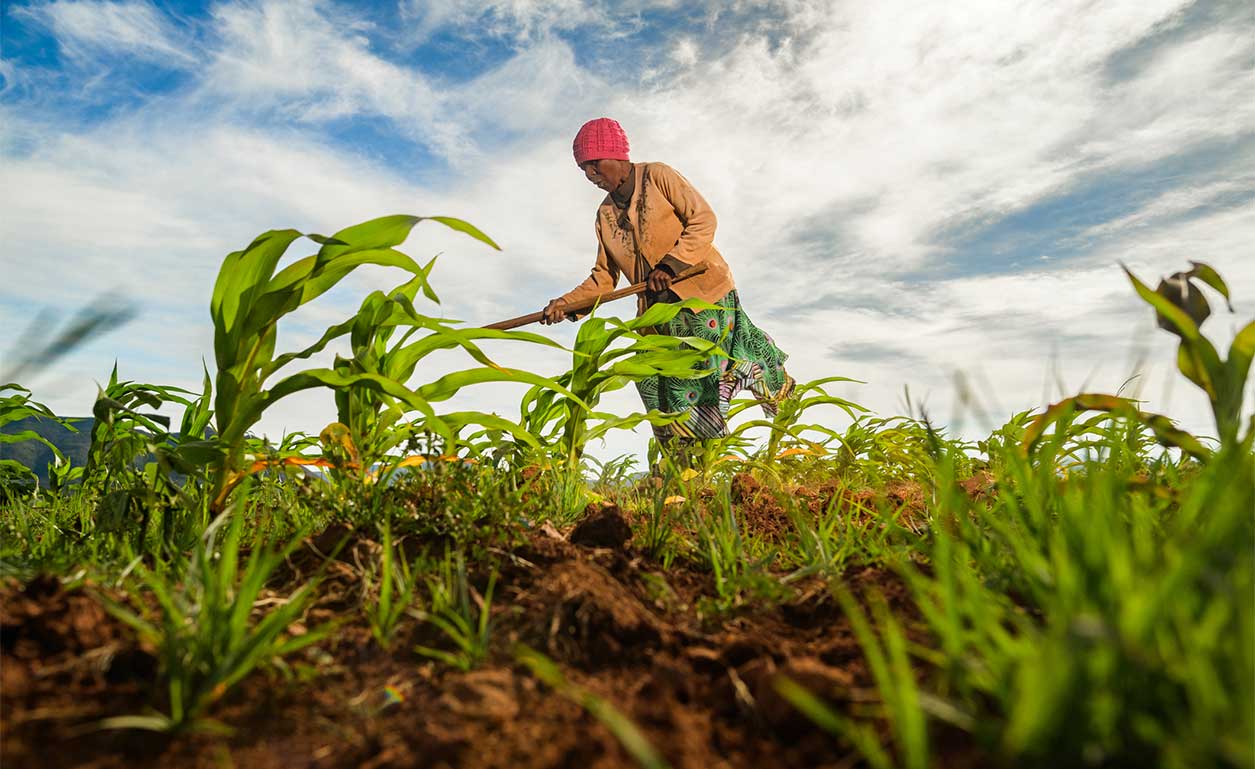
More than 37.1 percent of Ugandans derive their livelihoods directly or indirectly from agriculture. Most work for themselves and earn seasonally, operating outside the payroll systems through which social security contributions are traditionally collected.
Many are also smallholder and subsistence farmers who live from one harvest to the next, leaving little room for deliberate retirement planning.
In effect, Uganda’s largest workforce has the least retirement protection.
This is not merely a social welfare issue. It is an economic issue of national importance. If Uganda could successfully mobilise even a fraction of agricultural incomes into savings for the long term, the impact on both household welfare and national development would be transformative.
Understanding the challenges
The challenge begins with the nature of agricultural income itself.
Unlike salaried employees who receive predictable monthly wages, farmers earn irregular incomes. A coffee farmer may receive one or two large payments a year. A maize farmer may wait months between harvests. Dairy farmers experience seasonal fluctuations, while weather shocks can wipe out expected earnings altogether.
Traditional pension systems were designed around steady monthly payroll deductions. But agriculture does not operate that way.
A second challenge is financial literacy.
Many farmers are highly skilled producers but have limited exposure to concepts such as retirement planning, compound interest or wealth accumulation over the long term.
This is not irrational behaviour. When school fees are due, a child is sick or farm inputs must be purchased, saving for retirement 20 years away feels like a luxury, and understandably so.
Third is geography.
Many agricultural workers live in remote areas where access to formal financial services remains limited. Although financial inclusion has improved considerably over the past decade, distance from branches and service centres still discourages participation in formal savings schemes.
Then there is trust.
Farmers have seen cooperative societies collapse. Some have lost money in failed savings schemes. Others remain sceptical of financial institutions. Convincing them to lock away money for decades requires confidence that their savings will remain secure.
Finally, there is the challenge of scale.
Millions of smallholder farmers contribute relatively small amounts. Collecting and administering those contributions efficiently requires systems capable of operating at a very low cost.
The technology opportunity
Ironically, one of the biggest challenges, technology penetration, is increasingly becoming part of the solution.
Mobile money has penetrated deep into rural Uganda. Digital financial services now reach places where banks have never established branches. Coffee cooperatives, dairy processors, sugar companies and grain aggregators are increasingly digitising payments.
This creates an opportunity that barely existed a decade ago.
Contributions to retirement accounts can potentially be deducted automatically when farmers receive payments for produce. Rwanda’s Ejo Heza savings scheme already demonstrates how digital platforms can enrol informal workers and accept flexible contributions, while Kenya’s Mbao Pension Plan uses mobile money to make small pension contributions at low cost.
Uganda could build on these experiences by integrating pension deductions directly into agricultural payments.
A coffee farmer delivering beans to a cooperative, for example, could have a small percentage of the proceeds automatically transferred into a retirement account before the balance is paid out.
The process would resemble PAYE deductions for salaried workers, except that contributions would occur whenever agricultural income is earned rather than every month.
Technology makes this possible. The challenge is designing systems that are simple, affordable and trusted by farmers.
The voluntary savings problem
Many policymakers instinctively turn to voluntary savings schemes as the solution. The logic sounds appealing: create a pension product tailored for farmers and allow them to contribute whenever they wish.
Unfortunately, evidence from around the world suggests that purely voluntary systems rarely achieve significant participation among populations with low incomes.
Human beings are naturally inclined towards present consumption. Behavioural economists call this “present bias”. We prioritise today’s needs over tomorrow’s obligations.
This tendency is especially pronounced when incomes are uncertain. A farmer receiving a seasonal payout may genuinely intend to save for retirement. But between family obligations, social pressures and immediate consumption needs, the money often disappears before savings occur.
Uganda already has evidence of this behaviour. Many people understand the importance of saving, yet relatively few save consistently.
Expecting millions of farmers to voluntarily contribute substantial amounts to retirement accounts on a regular basis is therefore unrealistic.
Learning from The Fund’s success
The Fund’s greatest innovation is not investment management. It is compulsory saving.
Every month, contributions are deducted before workers can spend the money. The system removes the temptation to consume funds intended for the future.
Over time, small contributions accumulate into meaningful wealth, and the result has been extraordinary.
Savings mobilised from less than one fifth of Uganda’s workforce have created an institution capable of investing in government securities, real estate, infrastructure and capital markets. The Fund has become a regional financial powerhouse.
Imagine the possibilities if similar mechanisms could reach the agricultural sector.
The issue is not whether farmers can save. Many already do through livestock, land acquisition, rotating savings groups or simply keeping cash at home.
The challenge is channelling those savings into structured systems that provide retirement security while simultaneously mobilising capital for national development.
The cooperative advantage
Farmer organisations may hold the key.
Cooperatives already aggregate production, provide extension services and market produce. They also possess something critical: trust. Farmers are far more likely to participate in savings programmes introduced through institutions they already know.
A social security model linked to cooperatives could allow deductions at source while giving members visibility into their savings balances through mobile platforms.
The cooperative movement once played a central role in mobilising rural savings and investment. A modern version, powered by digital technology, could do so again.
Agricultural value chains also present an enormous opportunity. When a coffee exporter pays a cooperative, or a dairy processor pays a milk collection centre, an agreed percentage of each farmer’s proceeds could automatically be remitted into that farmer’s retirement account before the remaining balance is paid out.
The processor would simply act as a collection agent, much like an employer remits PAYE or NSSF contributions today, while the savings remain the property of the individual farmer.
This approach dramatically reduces collection costs while increasing participation.
Beyond farming: the agricultural value chain
It is important to remember that agriculture is not only about farming. It includes transporters, processors, warehouse operators, agricultural input dealers, exporters, traders and numerous service providers.
As Uganda pushes agro industrialisation, more people will enter formal segments of agricultural value chains where social security contributions can be collected more easily.
This is encouraging because it naturally expands the pool of contributors. Yet it also highlights the central challenge: the farmer remains the most difficult person to reach.
Many farmers are informal producers operating at subsistence level and living largely from hand to mouth. They have limited surplus income and face constant vulnerability to weather shocks, fluctuating prices and household emergencies.
Any social security solution that ignores this reality is unlikely to succeed.
Why this matters beyond retirement
The case for agricultural social security extends far beyond retirement security.
At the household level, it reduces vulnerability. Older farmers with retirement savings are less dependent on children and relatives. Families can invest more confidently knowing that future support obligations are reduced.
At the community level, savings pools provide resources that can be invested productively. At the national level, the implications are even greater.
One of the reasons poor countries remain poor is not necessarily because they lack resources, but because they fail to aggregate them.
Individually, households save very little. Collectively, millions of small savings become powerful pools of capital capable of financing roads, factories, power plants and industries.
The Fund has already demonstrated this principle. By aggregating contributions from less than one fifth of Uganda’s workforce, it has become one of East Africa’s largest institutional investors.
Extending this model to agriculture could become one of Uganda’s most transformative economic reforms. The resulting savings pool could finance infrastructure, housing, industrialisation, agro processing and agricultural transformation itself.
Few policy interventions offer such a powerful double dividend.
The way forward
Success will require a different mindset from conventional pension design.
First, products must accommodate seasonal incomes rather than monthly contributions.
Second, technology must make participation simple and inexpensive.
Third, financial literacy campaigns must help farmers understand the benefits of saving over the long term.
Fourth, partnerships among government, financial institutions, cooperatives and agribusinesses will be essential.
Most importantly, policymakers must recognise that relying entirely on voluntary participation is unlikely to achieve the desired scale. The goal should be to create mechanisms that make saving automatic whenever agricultural income is earned.
Just as formal workers contribute to social security before spending their salaries, farmers should have opportunities, and perhaps obligations, to save a small percentage of every harvest payment before consumption begins.
The principle is not punishment. It is protection against poverty in old age, economic vulnerability and the human tendency to sacrifice tomorrow for today.
The farmer under the mango tree may not think much about retirement when the harvest money arrives. Few of us do. But the purpose of public policy is not merely to accommodate human behaviour. It is to help people achieve outcomes they would struggle to achieve on their own.
Uganda has already demonstrated through The Fund that disciplined savings can transform individual lives and national fortunes.
The next frontier is taking that lesson from the payroll to the garden.
If we succeed, the greatest beneficiaries will not only be farmers. It will be the entire economy.
For in mobilising the savings of millions who live off the land, Uganda would unlock one of the largest pools of domestic capital in its history and perhaps take a decisive step towards the prosperity it has long sought.